Month-end closing · Article 09
Leasing
Applies to Odoo 19 · 20
Under a finance lease, the asset enters the company's assets as a fixed asset, and the liability to the leasing company is tracked as a loan, with interest and a residual value. Under an operating lease, the asset remains the lessor's, and the installments are rent. The flow in Odoo differs only for the finance lease.
When to use
- Cars, machines or equipment under a finance lease.
- Operating lease (long-term rental), with monthly invoices.
Before you start
- The Romania - Account Asset and Romania - Loans modules are installed: see Fixed assets and Loans.
- You have the contract and the repayment schedule from the leasing company.
Steps in Odoo
1. Record the receipt of the asset
Enter the leasing company's delivery invoice for the asset (or the receipt entry) with the fixed asset account (for example 2133). The counterpart is the leasing account, 167, not the vendor. Odoo creates the asset in draft.
2. Confirm the fixed asset
Complete and confirm the asset as for any fixed asset: see Fixed assets. Depreciation starts in the following month.
3. Create the lease as a loan
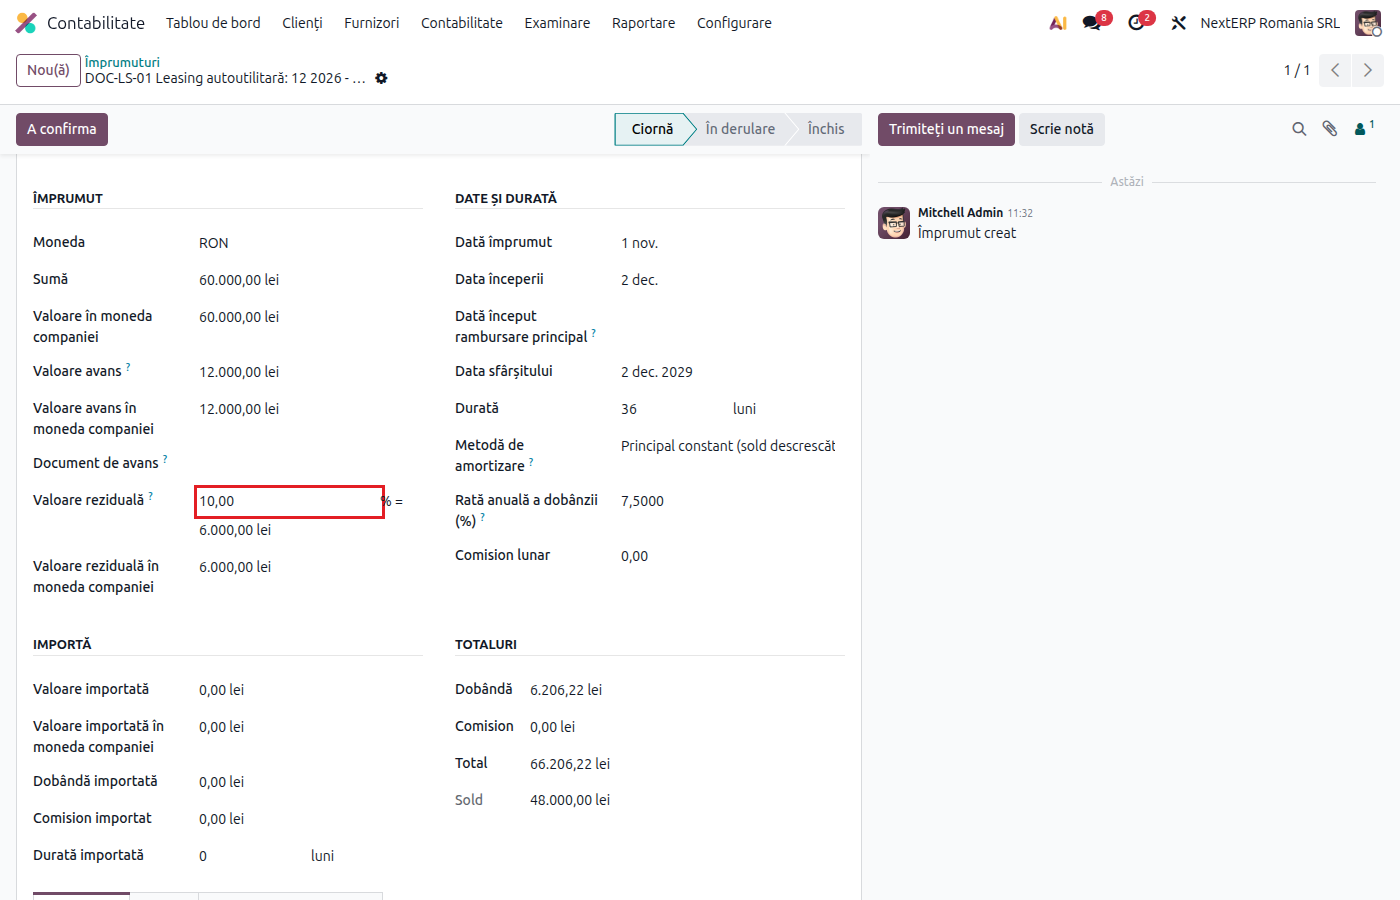
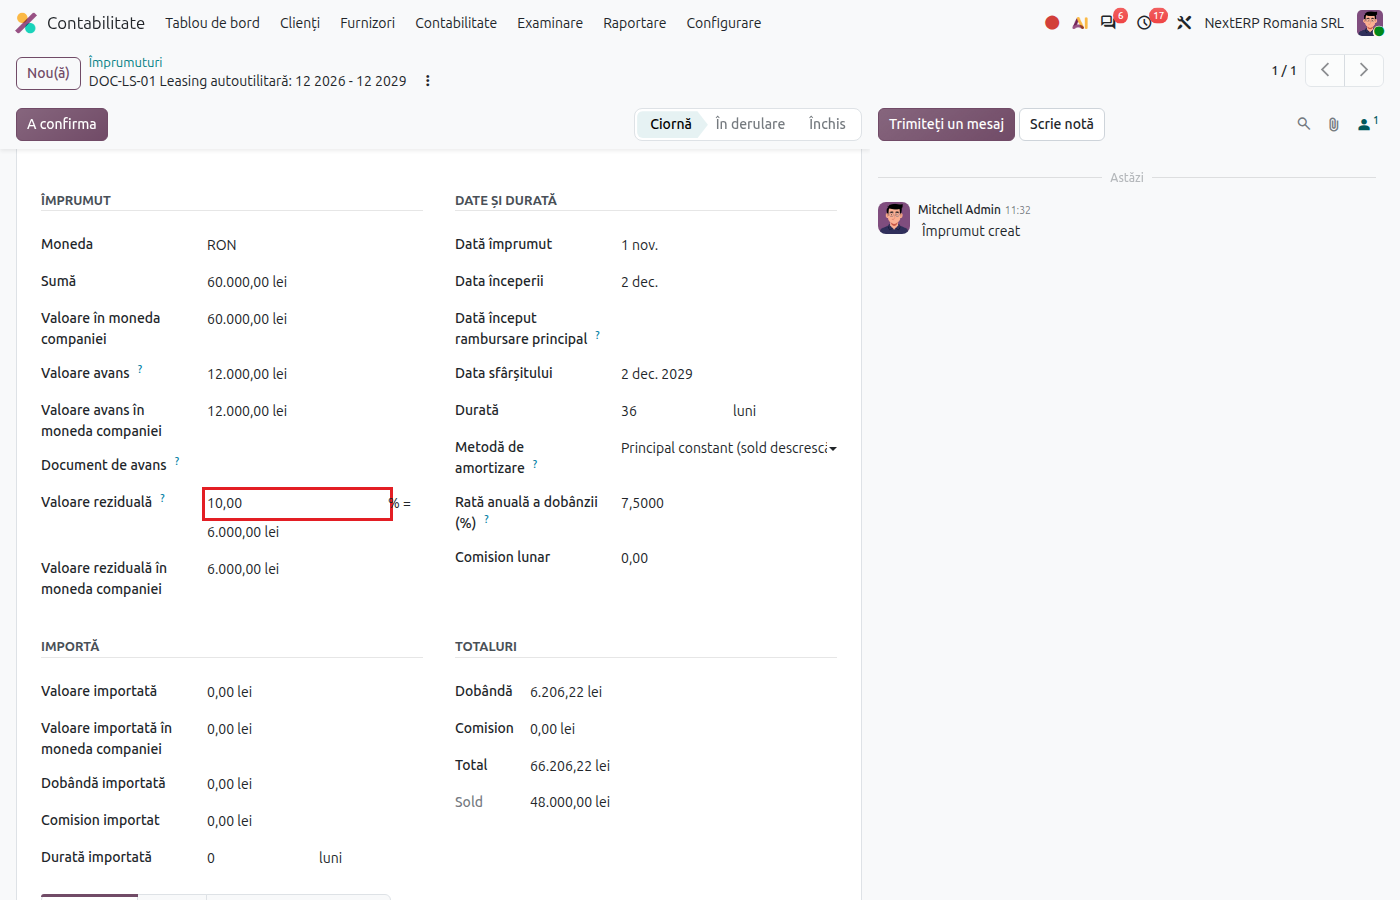
In Accounting › Accounting › Loans click New. Amount is the value of the asset, Advance Amount is the down payment, and Residual Value (%) or Residual Value is the buy-back value. Loan Account is 167.
4. Generate and confirm the schedule
Click Generate Schedule: the monthly installments amortize the value without the residual, and the last line, in bold, is the residual value. Compare with the leasing schedule and click Confirm.
5. Record the monthly installment invoices
The monthly invoice from the leasing company contains the principal and the interest, with VAT. On the bill, the principal line goes to 167, and the interest to the loan's interest account (1682), already credited by the monthly interest entry. The payment is made as for any vendor.
Variants
Operating lease
Do not create an asset or a loan. The monthly invoice is recorded as a service bill, on 612 (rent). If the invoice covers several months, see Prepaid expenses and deferred revenue.
Lease in foreign currency
Choose the currency on the loan. The balance of 167 is revalued every month: see Currency revaluation.
Buy-back
The last invoice contains the residual value. Its line goes to 167; after payment, the lease balance is zero and the loan can be closed.
Common mistakes
- Asset recorded against the vendor. The receipt of the asset is not a current liability; the counterpart is 167.
- Monthly installment posted entirely to expenses. Only the interest is an expense; the principal reduces the liability in 167.
- Residual value forgotten. The schedule no longer matches the leasing schedule. Fill it in before confirming.
For the accountant: legal framework, accounting entries, returns
Legal framework
- OG 51/1997 (Government Ordinance 51/1997) on leasing operations.
- Codul fiscal (the Romanian Fiscal Code), art. 28 para. (12)–(13) — depreciation by the user under a finance lease.
- OMFP 1802/2014 (the Ministry of Finance order with the accounting regulations) — lease accounting by the user.
Accounting entries
Example: car 60,000 lei, down payment 12,000 lei, monthly installment with principal 1,000 lei and interest 300 lei.
Receipt of the asset:
| DEBIT | CREDIT |
|---|---|
| 2133 — 60,000 | 167 — 60,000 |
The down payment invoice and its payment reduce 167:
| DEBIT | CREDIT |
|---|---|
| 167 — 12,000 4426 — 2,520 |
404 — 14,520 |
Interest for the month, recorded automatically by the loan:
| DEBIT | CREDIT |
|---|---|
| 666 — 300 | 1682 — 300 |
Monthly installment invoice:
| DEBIT | CREDIT |
|---|---|
| 167 — 1,000 1682 — 300 4426 — 273 |
404 — 1,573 |
For cars with mixed use, the deduction of VAT and expenses is limited to 50%: see Non-deductible VAT.
Operating lease, monthly invoice 1,000 lei + VAT:
| DEBIT | CREDIT |
|---|---|
| 612 — 1,000 4426 — 210 |
401 — 1,210 |
Link with the ANAF returns
| Return | What it takes |
|---|---|
| D300 (Decont de TVA, the VAT return) | the VAT on the installment invoices |
| D394 (the domestic supplies and purchases statement) | the leasing company's invoices |
| D101 (the corporate income tax return) | depreciation and interest (finance lease), rent (operating lease) |