Purchases · Article 09
Purchases from individuals
Applies to Odoo 19 · 20
Individuals do not issue invoices. When you buy goods from them (for example farm produce or a used item) or pay copyright fees, rent or a service contract, the supporting document is the purchase slip (borderou de achiziție), the contract or the payment statement. In Odoo, the transaction is recorded as a vendor bill in the person's name, without VAT, and the withheld tax is recorded separately.
When to use
- You buy goods from an individual, based on a purchase slip.
- You pay copyright fees or a civil service contract.
- You rent premises or a car from an individual.
Before you start
- The person exists as a vendor, with the personal identification number (CNP) in the tax ID field and the full address.
- A tax without VAT (for example 0% NT or 0% EXEMPT) is chosen on the vendor or on the bill, according to the classification set by the accountant.
Steps in Odoo
1. Create the bill in the person's name
In Accounting › Vendors › Bills click New and choose the person. For goods bought for stock, start from the purchase order and the receipt, as in Vendor bill.
2. Fill in the supporting document
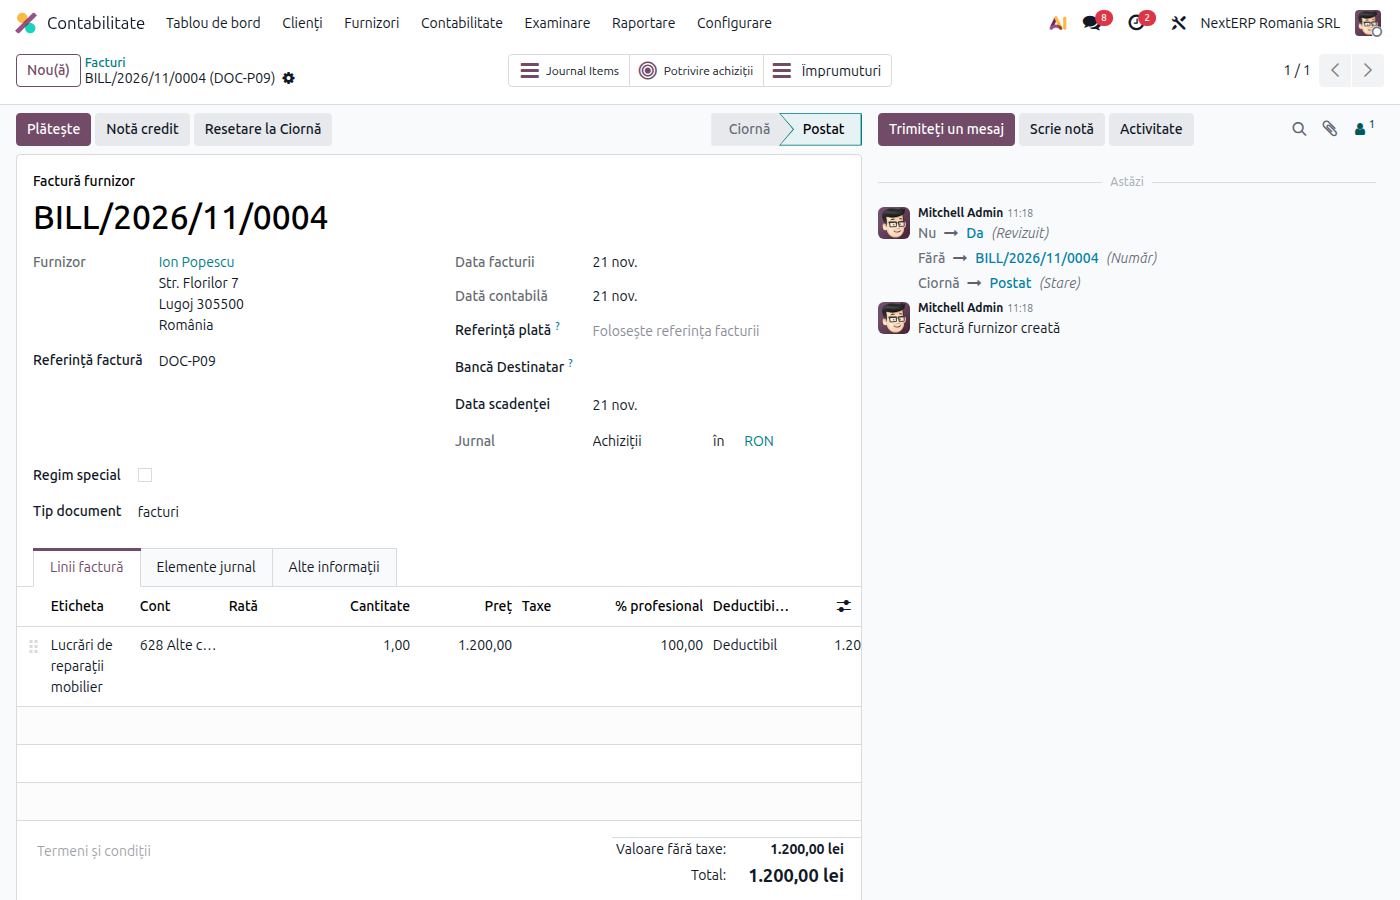
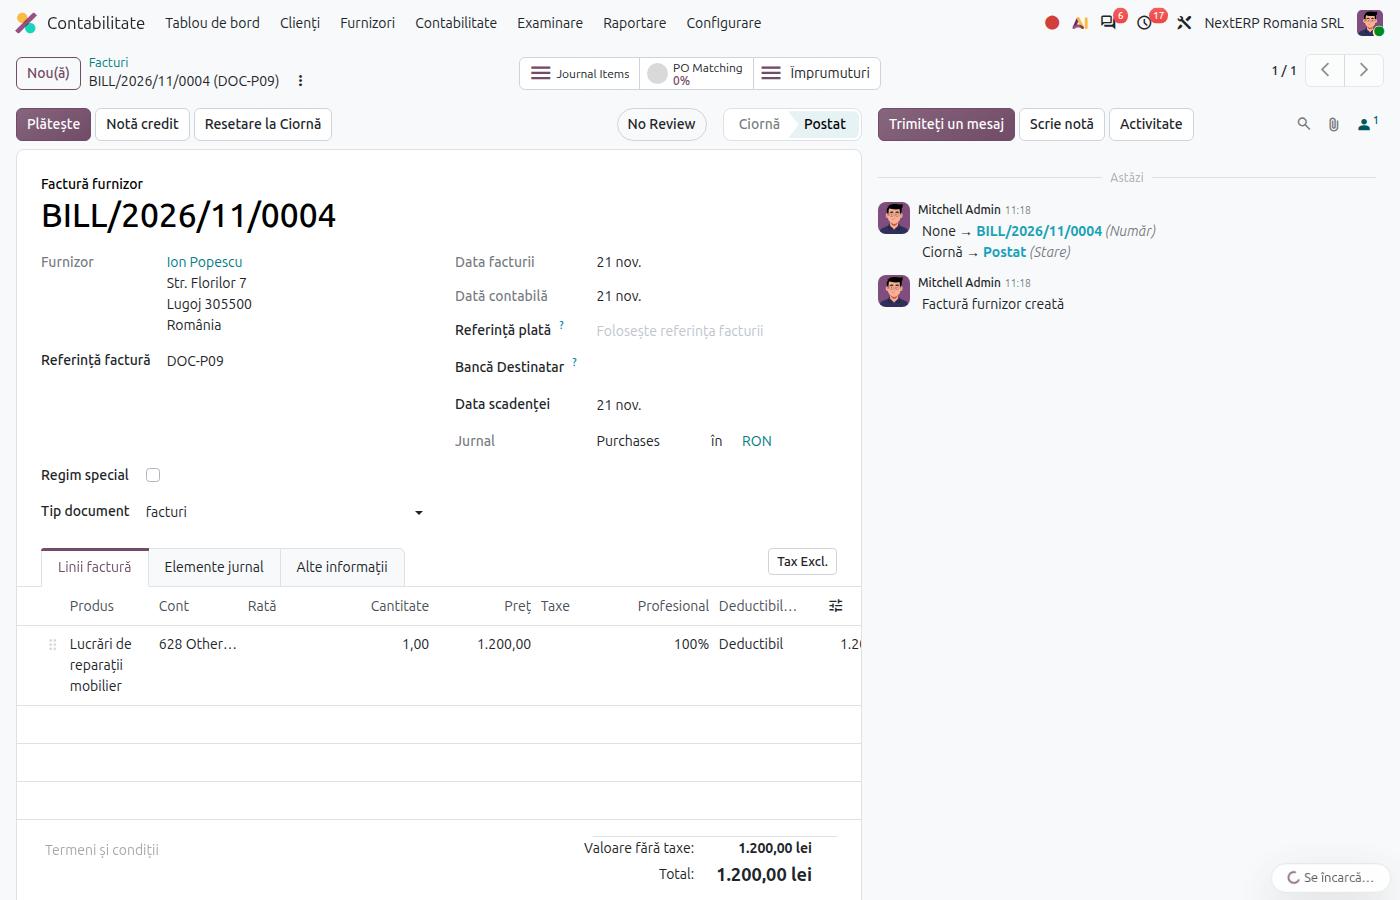
In Bill Reference enter the number of the purchase slip or of the contract, and in Bill Date its date. Attach the scanned document.
3. Fill in the lines
Enter the goods or service at the gross value from the contract, with the tax without VAT.
4. Confirm the bill
Click Confirm. The liability to the person appears on 401 at the gross value.
5. Record the withheld tax
The accountant records the tax and, where applicable, the withheld contributions through a journal entry in Accounting › Accounting › Transactions › Journal Entries. The person receives the net amount.
Variants
Goods bought for resale
Use the purchase order and the receipt: the goods enter stock at the value from the purchase slip.
Rent from an individual
Tax is withheld only if the person opted for withholding at source or if the law requires it for that type of income; the accountant sets the regime.
Common mistakes
- VAT put on the bill. An individual who is not registered for VAT does not charge VAT.
- Paying the full gross amount. Payment is made at the net value; the withheld tax is paid to the state budget.
- Authorized self-employed person (PFA) treated as an individual. A PFA issues its own invoice; record it like any vendor bill.
For the accountant: legal framework, journal entries, returns
Legal framework
- Codul fiscal (the Romanian Fiscal Code), Title IV — income tax: intellectual property rights (art. 70–73), transfer of the use of assets (art. 84), other income (art. 114–116), with withholding at source.
- OMFP 2634/2015 (the order on financial and accounting documents) — the purchase slip as a supporting document.
Journal entries
Example: copyright fees of 1,000 lei gross, 10% tax withheld (no contributions, for simplicity).
Vendor bill:
| DEBIT | CREDIT |
|---|---|
| 628 — 1,000 | 401 — 1,000 |
Withheld tax (journal entry):
| DEBIT | CREDIT |
|---|---|
| 401 — 100 | 446 — 100 |
The person is paid 900 lei, and the tax is paid to the state budget. The accountant sets the expense account and the tax and contribution rates, by type of income.
Link with the ANAF returns
| Return | What it takes |
|---|---|
| D100 | the tax withheld at source, monthly |
| D205 | the income and tax per beneficiary, yearly |
| D394 | purchases from individuals, where the law requires them |
D100 (Declarația privind obligațiile de plată la bugetul de stat) is the return for taxes owed to the state budget, D205 (Declarația informativă privind impozitul reținut la sursă) the yearly statement of tax withheld at source, and D394 the domestic sales and purchases listing.